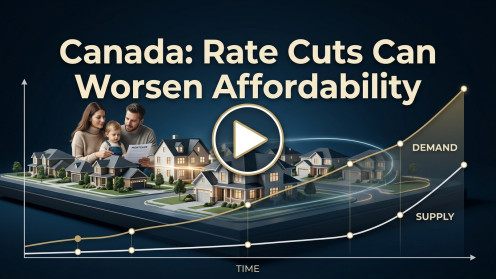
There’s a common belief that lowering interest rates directly solves housing affordability issues, but the reality is more complex—especially here in Canada. Central bank research shows that while rate cuts quickly increase housing demand (with a noticeable uptick in resales within just 18 to 24 months), the actual increase in new housing supply lags behind, often by two years or more. Strong job markets and easier lending can encourage buyers to act fast, but builders face a different set of challenges. Even when financing becomes more attractive, planning approvals and construction timelines—especially for multi-unit projects—mean it takes longer for new homes to reach the market. As someone with extensive experience in Toronto’s real estate landscape and across Ontario, I see firsthand how these dynamics play out. Ultimately, while rate cuts may eventually boost supply, the researchers agree: monetary policy alone isn’t a silver bullet for affordability. True solutions require a more coordinated approach that considers both demand and the practical realities of getting homes built.
Leave a Reply